Managing personal finances works best when you can see the whole picture and make decisions from the same set of numbers. This guide sets out a personal finance system you can maintain each month: measure your position, assign money to priorities, protect against setbacks and review whether your plan is working. It is a framework to adapt to your circumstances, not a rigid budget formula.
1. Create a Personal Financial Snapshot
Record your take-home income, cash balances, debts, investments and major financial commitments in one place. Use current balances rather than estimates wherever possible. This snapshot is your starting point; it does not need to be complicated to be useful.
2. Calculate Your Net Worth
Use Net worth = total assets − total liabilities. Assets may include bank balances, investments and property; liabilities may include outstanding loans and credit-card balances. Update the figure periodically and look at the trend over time. A single month can be affected by a large purchase or payment, so avoid judging progress from one number alone.
3. Map Your Cash Flow
Compare the money you actually receive with the money that leaves your accounts. Include irregular costs such as annual premiums, repairs, school fees or travel. If an expense occurs once a year, estimate its monthly share and set money aside in advance instead of treating it as a surprise.
4. Separate Commitments From Choices
Group spending into essential commitments, financial priorities and flexible purchases. This is more practical than labelling every expense as good or bad. When income changes or a bill rises, identify which flexible categories can be adjusted without missing important obligations.
5. Set a Small Number of Financial Priorities
Choose the most important goals for the next 6–12 months. Depending on your situation, these might include paying down expensive debt, building an emergency reserve, saving for a planned expense or beginning long-term investing. Give each goal a target amount and a realistic date. Too many simultaneous targets can spread available money too thinly.
6. Make a Debt Repayment Plan
List each debt with its balance, interest rate, minimum payment and due date. Keep up with required payments, then decide how to direct extra money. Paying down a high-interest balance can reduce future interest costs, while a repayment plan should still leave enough cash for essential needs and unexpected expenses.
7. Build an Accessible Reserve
An emergency reserve is intended for unplanned costs or a temporary income interruption, not routine shopping. Decide on a target based on your essential monthly expenses, job stability and dependants. Build it gradually in a suitable, accessible account; the right target can differ from one person to another.
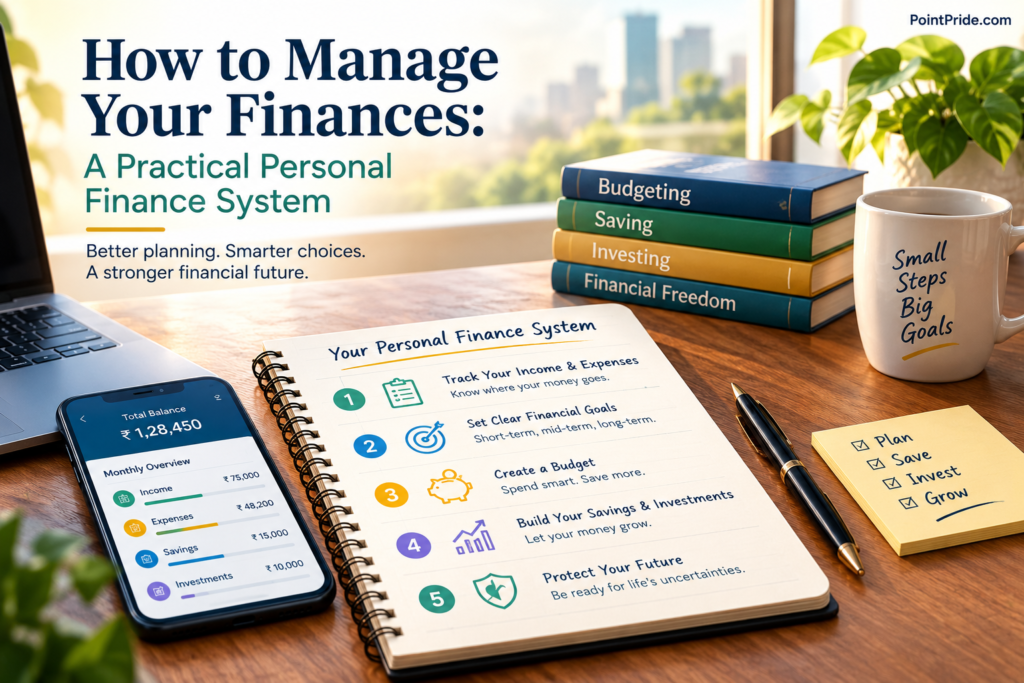
8. Protect Against Financial Setbacks
Review whether your health, life, vehicle or property insurance fits your responsibilities and local requirements. Keep nominee details and important financial documents up to date where applicable. Insurance is designed to address defined risks, so read exclusions, waiting periods, limits and renewal terms rather than choosing only by premium.
9. Match Each Goal to a Time Horizon
Money needed soon generally calls for more emphasis on stability and access. Goals many years away may allow a different investment mix, depending on your ability and willingness to accept losses. Do not put near-term essential money into a volatile asset simply because its potential return looks attractive.
10. Automate the Routine, Not Every Decision
Where practical, schedule transfers for savings and investments after income arrives and set reminders for bills. Automation reduces the chance of forgetting a routine action, but review amounts whenever income, expenses or goals change. Keep enough in the payment account to avoid failed transactions or overdraft charges.
11. Review Financial Behaviour, Not Just Totals
Look for recurring patterns: late fees, impulse purchases, unused subscriptions, repeated borrowing before payday or savings transfers that are routinely reversed. Pick one or two behaviours to improve at a time. A workable system is one you can sustain, not one that looks perfect on paper.
12. Use a Monthly Review
At the end of each month, compare planned and actual spending, check debt balances, update savings progress and note any unusual costs. Ask what changed, what worked and what needs adjustment. Keep the review brief enough that you will actually repeat it.
13. Do a Deeper Review Each Quarter
Every three months, check whether your goals and target dates still make sense. Review changes in income, family responsibilities, debt, insurance and investment allocations. A major life event may require an earlier review rather than waiting for the next quarter.
14. Keep Records Organised
Store statements, loan documents, insurance details, tax records and investment confirmations in a secure, organised place. Use strong account security and avoid sharing passwords or one-time codes. Good records make it easier to identify errors, complete applications and understand your position when a decision is needed.
15. Avoid Common System Failures
- Using an old budget that no longer reflects actual costs.
- Counting credit limits as available savings.
- Ignoring annual or irregular bills until they arrive.
- Taking investment risk with money needed soon.
- Changing goals every month without reviewing the reasons.
- Keeping important financial information scattered across messages and paper files.
A Simple Personal Finance Dashboard
You can track a small set of indicators: monthly take-home income, essential expenses, amount saved, high-interest debt outstanding, emergency-reserve balance and net worth. Add only the measures that help you make decisions. The goal is to notice changes early, not to collect numbers for their own sake.
Final Thoughts
A useful personal finance system combines clear information with repeatable actions. Start with a realistic snapshot, choose a few priorities, automate what is safe to automate and review the results regularly. Adjust the system as your income, obligations and goals change; consistency and informed decisions matter more than complexity.